
US ten-year Treasury hits 2002 highs as weak employment data cools Fed hike bets
The ten-year Treasury yield reached 5.34%, its highest level since 2002, as September payrolls rose by just 29,000 and reduced bets on a further rate rise in October.
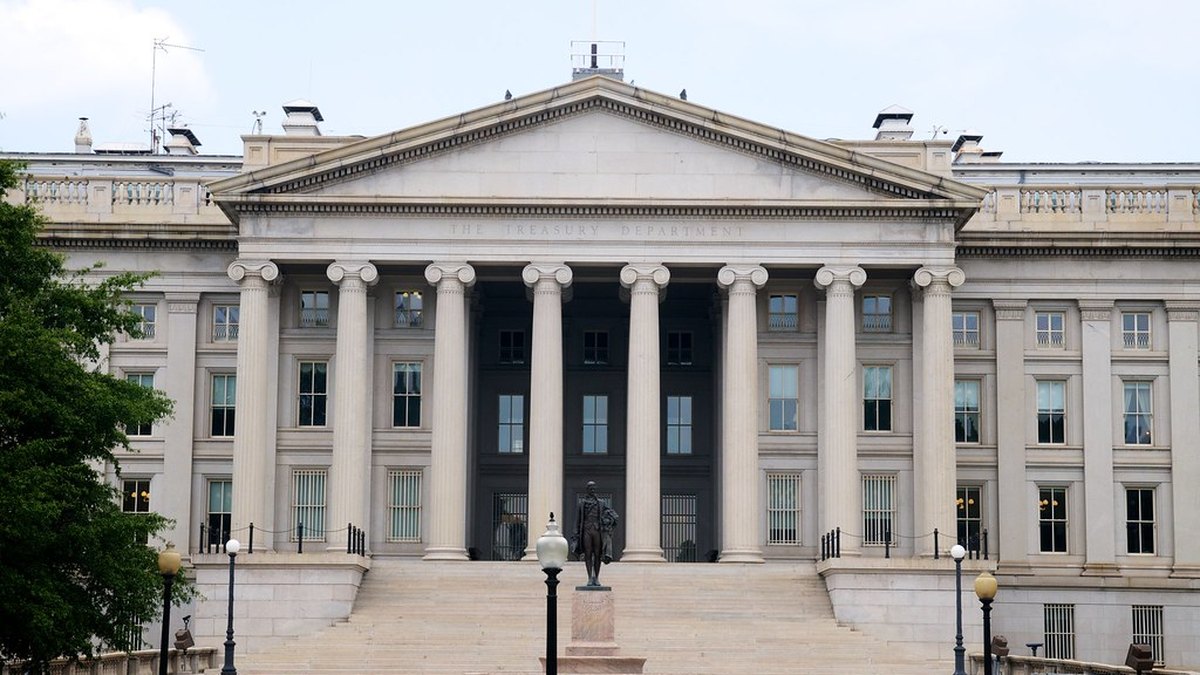
The United States Treasury building in Washington, epicentre of US public debt policy. Photo: @mikepick · CC BY 2.0 · via flickr
The US ten-year Treasury yield reached 5.34% on Thursday, its highest level since 2002—a twenty-four year high. The move came amid sustained selling of government debt: on Friday the yield closed around 5.28%, up from 5.24% the previous day.
Among the factors cited by financial coverage to explain the rise are elevated real rates, persistent inflationary and energy pressures, the resilience of economic activity and concerns about the US government’s deficit and financing needs. The Federal Reserve has maintained the federal funds rate in the 3.75% to 4.00% range, with an effective rate of 3.88% in recent sessions, according to Federal Reserve Bank of New York data.
September employment data
Non-farm payrolls increased by 29,000 jobs in September, according to the US Bureau of Labor Statistics, well below August’s 133,000. The unemployment rate rose to 4.2% from 4.1% the previous month. This is the most recent official reading on the US labour market.
The release sharply reduced market bets on a further interest rate rise at the October meeting. An important distinction: these are probabilities implied by interest rate futures prices, not a decision or signal from the central bank.
In bonds, however, the relief did not hold throughout the session. The ten-year yield fell in the immediate reaction to the data and then rose again, closing on Friday above Thursday’s level. Describing the employment report as a brake on the rise in yields does not correspond with what the closes showed.
A softer labour market reduces pressure on the Federal Reserve to raise rates again, but on its own has not reversed the sell-off in long-dated debt.
Equity and semiconductor reaction
Equities did respond to the data with gains. The S&P 500 closed on Friday around 7,700 points, up 0.7%, and the Nasdaq 100 finished near 30,800 points. Semiconductors led the move: ON Semiconductor rose around 6%, with gains also for Analog Devices, KLA, AMD, Lam Research and Marvell Technology, all between 1.5% and 3.5%.
The logic behind the move is well known: when the required yield on long-dated debt falls, future earnings of growth companies are discounted at more favourable rates and their valuations gain headroom. In this session that relationship worked in the immediate reaction to the data, even though the bond yield ended up closing higher.
What Morgan Stanley says about market breadth
Morgan Stanley expects the sharp divergence between the S&P 500 and weak market breadth—that is, the proportion of stocks participating in the index’s rise—to narrow in coming weeks. Its chief equity strategist, Michael Wilson, believes that if bond volatility does not moderate, the adjustment could occur through a convergence: some of the index’s strength would give way as participation from the rest of the market improves. This is one house’s forecast, not a market fact.
What to watch
The late-October Federal Open Market Committee meeting will be one of the main drivers in coming weeks, alongside the trajectory of long-dated Treasury yields, forthcoming inflation data and interventions by Committee members. The key question is whether the bond sell-off continues despite the cooling in employment.
Notice: informational content. Trading and investing carry risk of loss, including total loss of capital. Not investment advice.
Values in the box correspond to the last available close, Friday’s, while markets remain closed.
Related · Onyqdesk tools
Sources: US Bureau of Labor Statistics (September employment and unemployment); Federal Reserve Bank of New York (effective federal funds rate); market data from public providers integrated by Onyqdesk (ten-year Treasury yield, indices and Friday closing prices); Morgan Stanley (market breadth forecast, attributed in text).
🇪🇸 Versión en español: El bono estadounidense a diez años toca máximos de 2002 y el empleo débil enfría las apuestas de subida de la Fed
What if the next piece reached you before it happened?
Monday to Friday, 1h35 before the New York cash open: the pre-market with levels, the calendar and the trading idea of the day. On Sunday, the weekly wrap and the week ahead. Free. No spam. One click to unsubscribe.


Leave A Comment
You must be logged in to post a comment.