
US labour market cools in September as ten-year yield climbs to 5.28%
Job creation fell to 29,000 positions in September, its weakest reading in months, while unemployment rises to 4.2% and the ten-year yield hits fresh highs.
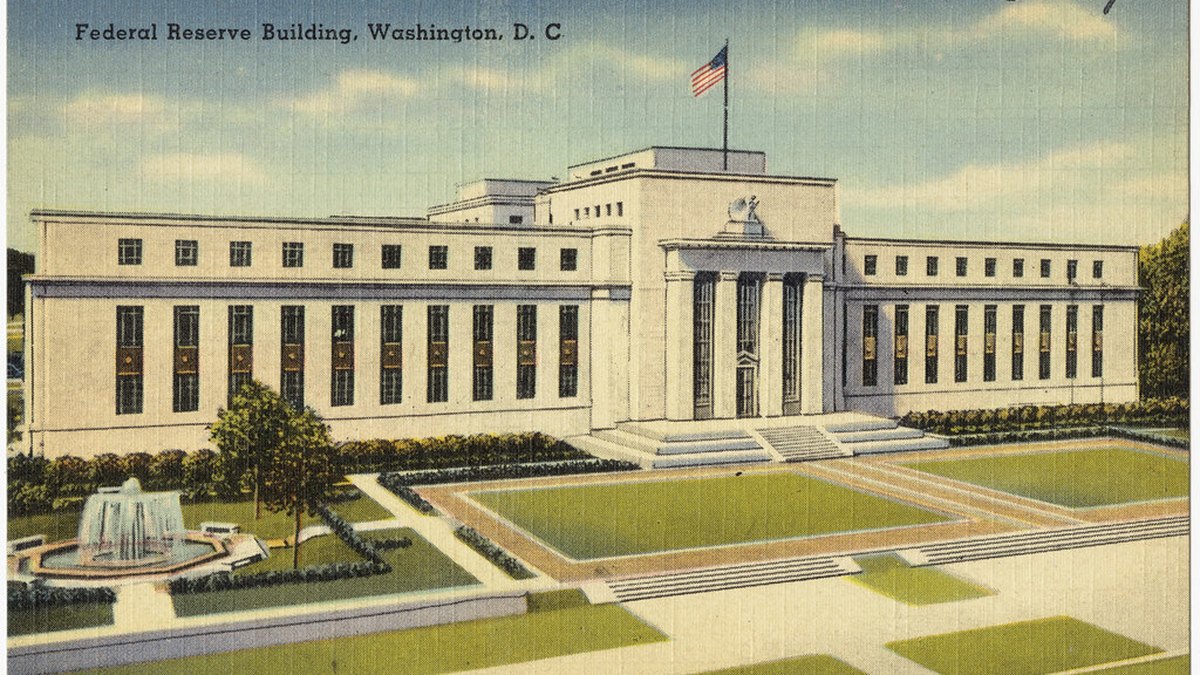
The Federal Reserve building in Washington, epicentre of US monetary policy. Photo: Boston Public Library · CC BY 2.0 · via flickr
The US labour market showed signs of weakness in September, with net job creation collapsing to just 29,000 non-farm positions, according to the latest data released by the Bureau of Labor Statistics. It is the weakest figure in several months and confirms a clear deceleration from the pace of prior months. At the same time, the unemployment rate rose by a tenth of a percentage point to 4.2%, the latest available reading for September.
The data arrives at a time when the Federal Reserve maintains its target range for interest rates between 3.75% and 4.0%, with an effective rate of 3.88% at the close of 1 October, the latest official figure. The combination of a cooling labour market and still-restrictive rates has once again put pressure on Treasury bonds: the ten-year yield climbed four basis points on Friday to 5.28%, its highest level in several sessions.
Persistent inflation and a resilient core
Although the immediate focus is on employment, the backdrop remains dominated by inflation. The headline CPI for August, the most recently published, registered a year-on-year increase of 3.4%, whilst the core index—which excludes energy and food—stood at 2.4% year-on-year. Both indicators reflect inflation that, whilst it has declined from 2022 peaks, remains distant from the Fed’s 2% target.
In monthly terms, headline CPI rose 0.3% in August, a pace that, if sustained, makes convergence towards the target difficult. The core index, for its part, has shown particular resistance, complicating any hasty reading of victory over prices.
A labour market losing momentum and inflation refusing to give ground constitute the worst possible scenario for monetary policy.
Wages and participation
Average hourly earnings rose slightly to $37.81 in September, from $37.76 in August. Although the advance is modest, the upward trend in nominal incomes remains a factor the Fed is watching closely, as it can fuel secondary inflationary pressures if not accompanied by productivity gains.
The combination of near-zero job creation and a rise in unemployment suggests that labour demand is cooling rapidly. That may ease wage pressures in coming months, but also raises the risk of an excessively abrupt cooling that results in a low-growth scenario.
Bond market reaction
The rise in the ten-year yield reflects uncertainty over the Fed’s next move. With the effective rate at 3.88%, the market is pricing in that any immediate cut is far from guaranteed, especially if core inflation does not yield more clearly. The bond rally is also putting pressure on equities, which had already shown volatility in recent sessions.
Investors are caught between two forces: a labour market that is cooling and which in theory would justify a more accommodative stance, and inflation that is not yet showing signs of surrender. In this context, the ten-year remains the thermometer of expectations on rates and growth.
What to watch
The next CPI reading, for September, will be key to gauging whether the employment deceleration is accompanied by relief on prices. FOMC minutes and any statements from Fed members on their willingness to ease monetary policy will also bear watching. For now, the message remains one of caution: the path to 2% inflation is longer than expected, and employment is beginning to pay the price.
Notice: informational content. Trading and investing carry risk of loss, including the entirety of capital. This is not investment advice.
Related · Onyqdesk tools
Sources: official US series (BLS, Federal Reserve, Treasury) via Alpha Vantage and news aggregator.
🇪🇸 Versión en español: El mercado laboral estadounidense se enfría en septiembre y el bono a diez años repunta hasta el 5,28%
What if the next piece reached you before it happened?
Monday to Friday, 1h35 before the New York cash open: the pre-market with levels, the calendar and the trading idea of the day. On Sunday, the weekly wrap and the week ahead. Free. No spam. One click to unsubscribe.


Leave A Comment
You must be logged in to post a comment.